Korea Basic Pension 2026: ₩349,700 a Month, the Income Cut-Off and How to Apply
Haesul Economy desk (AI-assisted). Last checked: 2026-11-13 (KST); first published 4 November 2026. The cut-off and amounts are reset by ministry notice each January; the 2026 notice came out on 1 January 2026, and January 1, 2027 is 49 days from November 13. The 2027 budget plan was re-read on the MOHW press release on Nov 13. Originally written as of 4 November 2026 (KST), based on the Ministry of Health and Welfare (MOHW), Government24 and the Ministry of Government Legislation’s EasyLaw service. This is general information, not financial or legal advice.
2027 in one line: the government’s 2027 budget plan keeps the 70% rule but would pay ₩380,000 a month to the lowest-income 30% and cut the couple reduction to 10% for the lowest 45%; it still needs the National Assembly (details below).
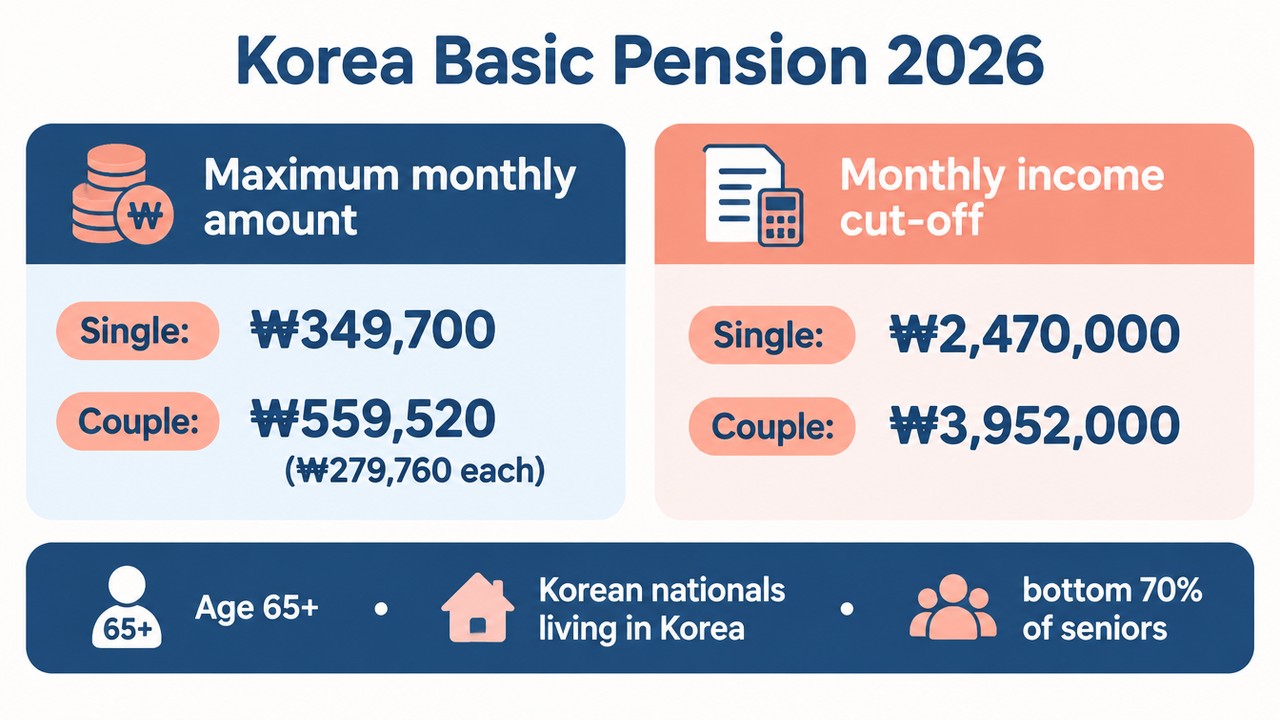
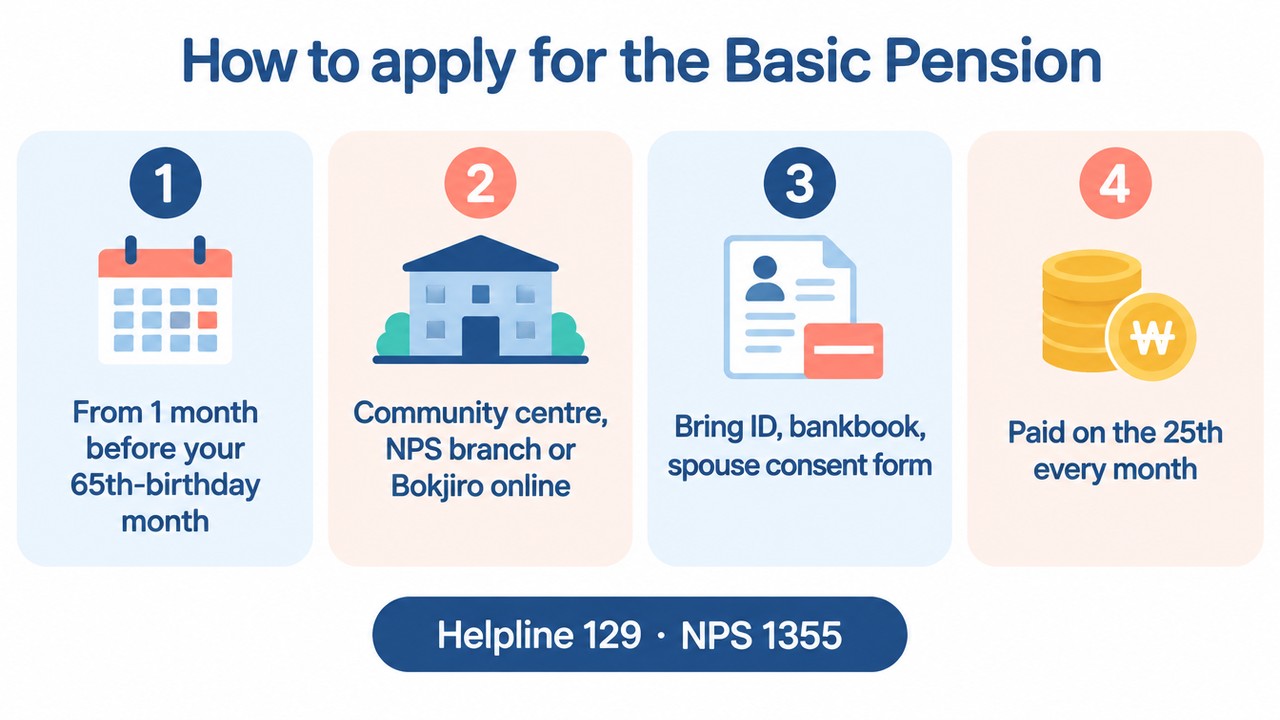
Quick answer: Korea’s Basic Pension (기초연금) pays up to ₩349,700 a month in 2026 to a single person aged 65 or older, and up to ₩559,520 for a couple (₩279,760 each). You qualify if your household’s monthly “income recognised amount” (소득인정액) is ₩2,470,000 or less if single or ₩3,952,000 or less as a couple. It is not automatic: you apply at a community centre, a National Pension Service (NPS) branch or online through Bokjiro, starting one month before the month of your 65th birthday.
What the Basic Pension is (and what it is not)
The Basic Pension is a tax-funded monthly payment for older residents. It is separate from the National Pension (국민연금), which you earn by paying contributions while you work. You do not need any contribution record to receive the Basic Pension, and you can receive both at the same time, although a large National Pension can reduce the Basic Pension (see below).
The ministry sets the income cut-off each year so that about 70% of people aged 65 and over qualify. For 2026 the MOHW raised the single-person cut-off from ₩2,280,000 to ₩2,470,000 (+8.3%), because older people’s pension income, business income and property values rose. In the ministry’s own words, most actual recipients have much lower figures: about 86% had an income recognised amount under ₩1.5 million (September 2025 data).
Who can apply:
- Aged 65 or over. In 2026 that means people born in 1961 or earlier.
- A Korean national living in Korea with a resident registration. Foreign nationals are not covered; this is a citizens’ benefit, unlike National Health Insurance.
- Household income recognised amount at or below the cut-off.
- People who receive a public-service pension (civil servants, private school teachers, military, special post offices) and their spouses are excluded in principle, with some exceptions (for example, people who took a lump sum instead of a pension).
2026 amounts and cut-offs at a glance
| Item (2026) | Single (no spouse) | Couple |
|---|---|---|
| Monthly income cut-off (선정기준액) | ₩2,470,000 | ₩3,952,000 |
| Maximum monthly Basic Pension | ₩349,700 | ₩559,520 (₩279,760 each) |
| 2025 cut-off, for comparison | ₩2,280,000 | ₩3,648,000 |
| Payment day | 25th of each month (the day before if it falls on a weekend or holiday) | Same |
Sources: MOHW press release of 1 January 2026; MOHW Notice No. 2026-156; Government24 Basic Pension service page; EasyLaw.
The couple figure is lower per person because, when both spouses receive the Basic Pension, each amount is cut by 20%: ₩349,700 × 0.8 = ₩279,760, and two of those make ₩559,520.
How the “income recognised amount” is worked out
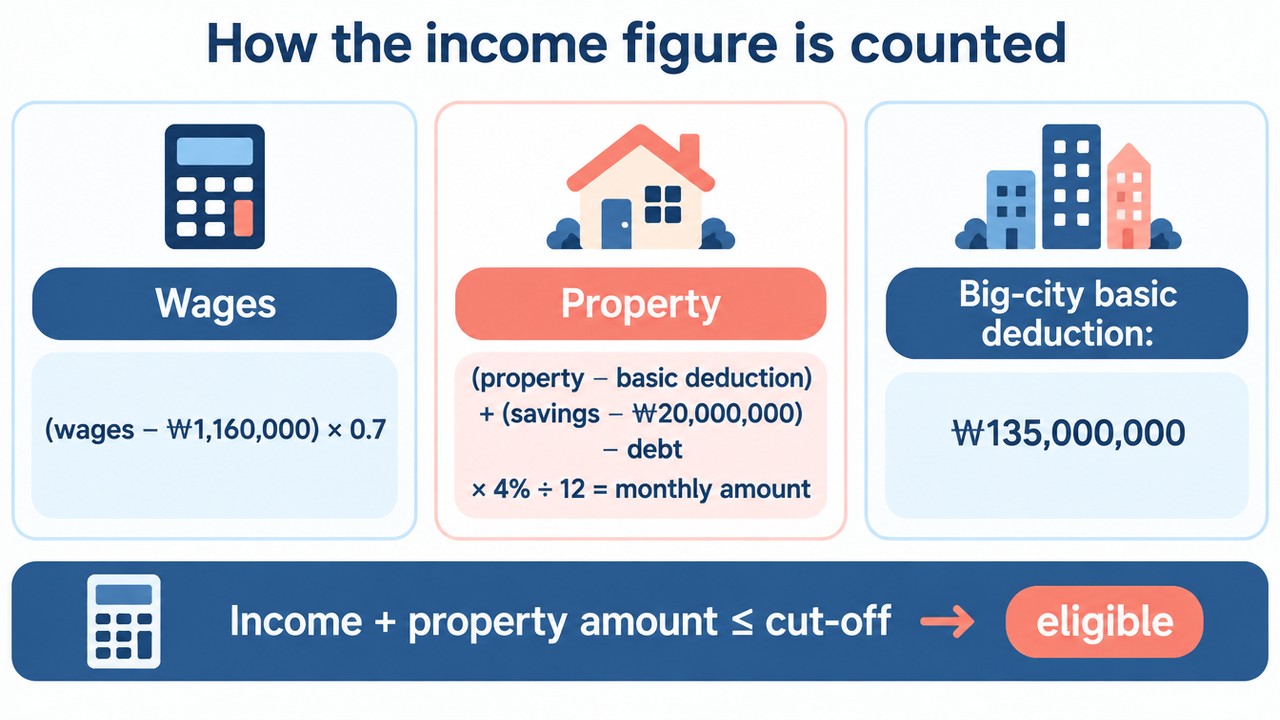
This is where most confusion comes from. The cut-off is not your salary. It is a single monthly figure that adds your income and a monthly value for your property, for you and your spouse only. Your children’s income and assets are not counted, with one exception: if you live in a house owned by your child and its official standard value is ₩600 million or more, a notional “free rent” income is added.
1. Monthly income part
- Earned income (wages): first ₩1,160,000 is deducted, then only 70% of the rest counts: (wages − ₩1,160,000) × 0.7.
- Other income counts in full: business income, property income (such as rent and interest), public transfer income such as the National Pension.
2. Property part
- General property (housing, land, buildings) minus a basic property deduction: ₩135 million in large cities, ₩85 million in mid-sized and small cities, ₩72.5 million in rural areas.
- Financial assets (savings, deposits, insurance) minus ₩20 million.
- Minus debts (loans, unpaid card balances and similar).
- The result is multiplied by the conversion rate of 4% a year and divided by 12 to get a monthly figure.
- Luxury cars and golf or condo memberships are counted at their full value per month, which in practice disqualifies most owners.
Sources: Government24; Enforcement Rule of the Basic Pension Act, Article 4 (4% rate); MOHW Notice No. 2026-156 (₩1,160,000 deduction, ₩600 million rule).
Worked example: a single 67-year-old in Seoul
This is our illustration using the official formula. Your own figures are assessed by your local office and the NPS.
| Step | Figure | Calculation |
|---|---|---|
| Monthly wages from a part-time job | ₩2,000,000 | |
| Earned income counted | ₩588,000 | (2,000,000 − 1,160,000) × 0.7 |
| Apartment, official value | ₩300,000,000 | |
| Minus big-city deduction | ₩165,000,000 | 300,000,000 − 135,000,000 |
| Savings minus ₩20 million | ₩10,000,000 | 30,000,000 − 20,000,000 |
| Property counted (no debt) | ₩175,000,000 | 165,000,000 + 10,000,000 |
| Property as monthly income | ₩583,333 | 175,000,000 × 4% ÷ 12 |
| Income recognised amount | ₩1,171,333 | 588,000 + 583,333 |
| Cut-off (single) | ₩2,470,000 | Eligible: 1,171,333 ≤ 2,470,000 |
Because ₩1,171,333 plus the full ₩349,700 is still below the ₩2,470,000 cut-off, this person would get the full amount, provided they do not receive a large National Pension (next section).
Near the line: if someone’s income recognised amount were ₩2,300,000, adding the full ₩349,700 would take them to ₩2,649,700, above the cut-off. The law then reduces the Basic Pension by the excess, so they would get roughly ₩170,000 (₩2,470,000 − ₩2,300,000) instead of ₩349,700. This “income reversal” reduction stops people just under the line ending up better off than people just over it.
When the amount is reduced
According to EasyLaw and the NPS, three situations cut the monthly payment:
- Both spouses receive it: each amount is reduced by 20%.
- Near the cut-off: as in the example above, the payment is reduced so that income plus Basic Pension does not exceed the cut-off.
- A larger National Pension: if your National Pension is more than ₩524,550 a month (150% of the ₩349,700 standard amount) and its “income redistribution portion” (A-benefit) is more than ₩262,270, the NPS applies a linked reduction. The Basic Pension can then be cut by up to 50%. You can look up both figures on the NPS website or by calling 1355.
Payments also stop if you stay abroad for 60 days or more in a row, and end if you lose Korean nationality or emigrate.
If you are still years away from 65, our guide to the National Pension age by birth year explains when that separate pension starts.
What the 2027 plan would change
Rechecked on November 13, 2026 (MOHW): the 2027 MOHW budget, approved by the Cabinet on 1 September 2026, raises Basic Pension spending from ₩23.1 trillion to ₩25.7 trillion (+11%) for three changes: a tiered “more for the lowest incomes” payment (3.48 million people), a smaller couple reduction (2.34 million) and support for public-service pension recipients and their spouses (110,000). The single-person tiers below are from Yonhap’s report of the same briefing; the couple figures are MOHW’s.
| Income group (65+) | Single, per month (plan) | Couple, both receiving (plan) |
|---|---|---|
| Lowest 0–30% | ₩380,000 | ₩684,000 (from ₩560,000) |
| 30–45% | ₩359,000 | ₩646,000 (from ₩560,000) |
| 45–70% | ₩350,000 | unchanged 20% couple reduction |
Sources: MOHW, 1 September 2026 (budget, couple figures); Yonhap, 1 September 2026 (single-person tiers, 20% → 10% couple reduction). The couple figures match the singles with a 10% reduction: ₩380,000 × 2 × 0.9 = ₩684,000 (our calculation).
Worked example (our calculation): a couple in the lowest 30% who now get the full ₩559,520 would receive ₩684,000 under the plan, +₩124,480 a month; a single person in that group would go from ₩349,700 to ₩380,000 (+₩30,300).
When: not yet law. The tiers and the couple change need an amendment to the Basic Pension Act, and MOHW said it aims to pass it this year and start in April 2027 (Newsis, 31 August 2026). The Constitution requires the National Assembly to pass the budget 30 days before the fiscal year begins, i.e. by 2 December 2026, 19 days from November 13. Until then, the 2026 amounts above apply, and the January notice resets the cut-off as usual. Foreign nationals remain outside the scheme.
How to apply
| Step | What to do |
|---|---|
| When | From one month before the month you turn 65. Payment starts from the month you apply (or your birthday month if you applied early) |
| Where | Any community centre (읍·면·동 행정복지센터) or NPS branch, regardless of your address, or online at Bokjiro (bokjiro.go.kr) |
| Bring | ID card, bankbook copy for your own account, your spouse’s consent to share financial information, a lease contract if you rent |
| Can’t travel? | Ask the NPS (1355) for a home visit to take the application |
| Questions | MOHW helpline 129, NPS 1355 |
If you were rejected before and your income or property has since fallen, you can apply again. You can also ask to be kept on the “wish to receive” history list (수급희망 이력관리) so the office checks your eligibility again each year.
Many applicants are also sorting out health insurance or a family member’s payslip at the same time. Our guides to Korea health insurance for foreigners in 2026 and payslip deductions for the four social insurances cover those.
Practical checklist before you apply
- Check your birth month. In 2026, a person born in April 1961 can apply from March 2026 and is paid from April.
- Gather debt papers. Loans reduce your property figure, so bring statements.
- Know your National Pension figures if you receive one: the monthly amount and the A-benefit, from the NPS.
- Plan long trips. Two months or more abroad pauses the payment.
- Re-check every January. The cut-off and the standard amount are reset each year by ministry notice.
Frequently asked questions
Q. How much is the Korea Basic Pension in 2026?
Up to ₩349,700 a month for a single person and up to ₩559,520 for a couple who both receive it (₩279,760 each). The actual amount can be lower depending on income and any National Pension.
Q. What is the Basic Pension income cut-off for 2026?
A monthly income recognised amount of ₩2,470,000 for a single person or ₩3,952,000 for a couple. It combines income and a monthly value of property; it is not the same as salary.
Q. Can foreigners get Korea’s Basic Pension?
No. It is for Korean nationals aged 65 or over who live in Korea with a resident registration. Foreign residents may have National Pension and health insurance rights, but not the Basic Pension.
Q. Can I get the Basic Pension and the National Pension together?
Yes. But if your National Pension is above ₩524,550 a month and its A-benefit portion is above ₩262,270, the Basic Pension is reduced, by up to half.
Q. When should I apply for the Basic Pension?
From one month before the month of your 65th birthday, at a community centre, any NPS branch, or online at Bokjiro. It is not paid automatically.
Q. Will the Basic Pension go up in 2027?
Probably for lower-income pensioners, but it is not final. The 2027 budget plan (MOHW, 1 September 2026) would pay ₩380,000 a month to the lowest-income 30% and ₩359,000 to the 30–45% group, and cut the couple reduction from 20% to 10% for the lowest 45%. It needs the National Assembly; MOHW aims to start in April 2027. The yearly cut-off notice comes out around January 1.
Related reading
- Korea NPS catch-up before the 10% rate
- Korea long-term care grades: 2027 limits
- Korea health insurance for foreigners: the 2026 floor and 2027 rate
Sources
- Ministry of Health and Welfare, 2027 MOHW budget proposal press release (Basic Pension: ₩23.1T → ₩25.7T, tiered payment, couple reduction), 1 September 2026 (checked 13 November 2026)
- Yonhap News, “[2027예산] 기초연금 70% 틀 유지…소득 하위 30% 月3만원 더 준다”, 1 September 2026 (checked 13 November 2026)
- Newsis, 2027 Basic Pension reform: April 2027 target, 31 August 2026 (checked 13 November 2026)
- Ministry of Health and Welfare, press release: 2026 Basic Pension cut-off ₩2.47 million for single households, 1 January 2026 (checked 4 November 2026)
- Ministry of Health and Welfare, Notice No. 2026-156 on Basic Pension cut-offs, standard amount and income calculation, law.go.kr (figures cross-checked 4 November 2026 against Government24 and EasyLaw)
- Government24, Basic Pension service information, last updated 14 August 2026 (checked 4 November 2026)
- Ministry of Government Legislation, EasyLaw, Basic Pension (checked 4 November 2026)
- Enforcement Rule of the Basic Pension Act, Article 4 (4% conversion rate) (checked 4 November 2026)
- National Pension Service, National Pension benefit and A-benefit lookup (2026 linked-reduction thresholds) (checked 4 November 2026)
- Korea.kr policy briefing, Basic Pension (eligibility: Korean nationals resident in Korea) (checked 4 November 2026)
This article is general information, not financial or legal advice. It was written with AI assistance and fact-checked against official sources. Your eligibility is decided by your local office and the NPS.
7 Comments