Korea National Pension Catch-Up and Voluntary Continue After 60 (2026)
Haesul Economy desk (AI-assisted). Last checked: 2026-11-11 (KST); countdown updated 2026-11-13; first published 7 November 2026. The contribution rate rises from 9.5% to 10% on January 1, 2027 — 49 days from November 13. The catch-up rate rule was re-read in National Pension Act Article 92 and the rate path on the MOHW pension-reform Q&A on Nov 11. Based on the National Pension Service (NPS) pages for additional contribution (추후납부 / 추납) and voluntary continued enrollment (임의계속가입), the Ministry of Health and Welfare (MOHW) national-pension policy page, and the MOHW income-base notice for July 2026–June 2027. This is general information, not financial, tax or legal advice. Confirm your own months, base and bill with NPS (1355) or a licensed adviser before you apply or pay.
Quick answer: Timing matters this year. A catch-up bill is priced at the contribution rate of the month it is due, and that rate goes from 9.5% to 10% on January 1, 2027. Apply for a lump-sum catch-up by Monday, November 30 (17 days left from November 13) and the bill normally falls due on December 31 at 9.5% (National Pension Act Art. 92; MOHW). Two year-end pension actions often get mixed up. Catch-up (추납) lets a currently enrolled member pay for past unpaid exemption or exclusion months using today’s premium, up to under 10 years (119 months max, including qualifying post-1988 military service with documents). Voluntary continued enrollment (임의계속가입) lets someone who has hit age 60 keep contributing until the day before their 65th birthday — including foreign members — so short careers can still reach a pension. The 2026 contribution rate is 9.5%. The standard monthly income base from July 2026 to June 2027 sits between ₩410,000 and ₩6,590,000. Voluntary members’ catch-up premium is capped using the 2026 A-value ₩3,193,511 × rate. Workplace voluntary continue means the worker pays the full 9.5%, not half. Other voluntary-continue members use a median base of ₩1,013,000 from April 2026. Bills for approved catch-up usually mail around the 11th–15th of the month after you apply and are due by month-end; you may pay lump sum or in up to 60 monthly installments (installment interest = 1-year time-deposit rate).
If you are also filling an IRP or pension-savings account for the year-end tax credit, that is a separate NTS track — see our IRP and pension savings tax credit guide. For when old-age pension starts by birth year, see national pension age by birth year. The four social-insurance lines on a payslip (including the employee half of national pension at workplaces) are explained in our payslip guide. Basic pension for low-income seniors is a different programme — basic pension 2026.
Catch-up (추납) in plain English
NPS describes catch-up as a chance to pay, at the premium that applies when you apply, for months you could not pay earlier. Those months then count as insured periods. It is optional, not forced.
Who can newly apply. You must currently be an income-reported member or a voluntary / voluntary-continued member. If you have already lost eligibility, you generally cannot newly apply. Already-approved catch-up bills can still be paid while collection rights remain (with late interest after the due date); death or starting a pension typically closes payment.
Which past months qualify (NPS list).
| Period type | Notes from NPS |
|---|---|
| Contribution exemption (납부예외) | Business stop, job loss, disaster and similar exemption months |
| Exclusion after at least 1 month paid | Months excluded after you had paid at least once |
| No-income spouse exclusion | From 1 Apr 1999 |
| Basic-livelihood recipient exclusion | From 1 Apr 2001 |
| Missing-person exclusion (1 year+) | From 1 Jan 2008 |
| Under-18 workplace exclusion | From 29 Jul 2015 |
| Military service from 1 Jan 1988 | Soldier periods already counted in other public pensions excluded; with military periods, max still 119 months |
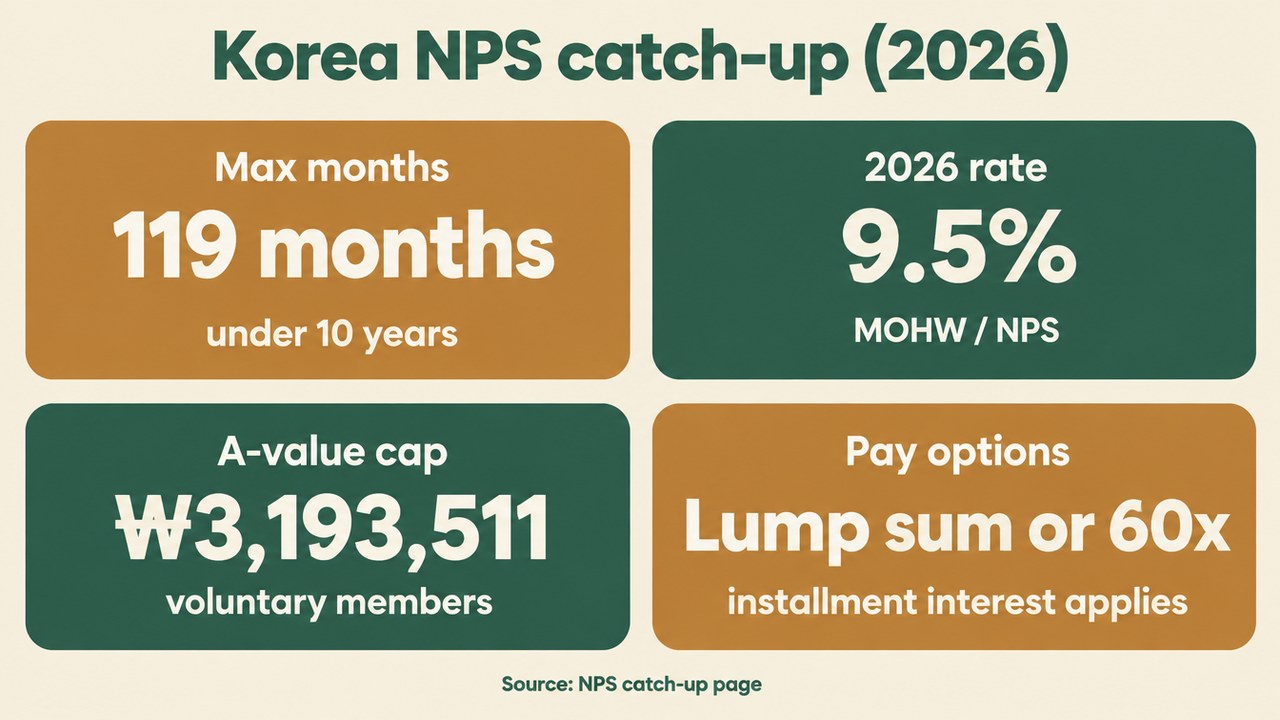
Ceiling. Catch-up is limited to under 10 years — NPS states a maximum of 119 months, including qualifying military service months when those are claimed with documents.
Documents, bill timing and how the premium is calculated
Documents NPS asks for.
- A detailed marriage-relation certificate with resident registration numbers visible is required for catch-up; without it the application is not processed. Pre-2008 divorce or bereavement cases may also need a family-register extract (제적등본).
- Military months: military service certificate and/or resident registration abstract that shows service history.
- Under-18 workplace exclusion months: typically an NHIS eligibility (자격득실) certificate and similar proofs.
Payment options. Pay the catch-up premium in one lump sum, or in monthly installments up to 60 times. Installments add interest at the 1-year time-deposit rate.
Bill calendar. After you apply, NPS says the bill is mailed around the 11th–15th of the following month and is due by the end of that month. One unpaid reminder may be sent; NPS states catch-up is not sent to compulsory delinquency collection the way ordinary arrears can be.
Formula (NPS).
Catch-up premium = [standard monthly income of the application month] × [contribution rate of the due month] × [number of months]
For voluntary members, the premium used inside that formula is capped at A-value of the application month × due-month rate. NPS posts the 2026 A-value as ₩3,193,511 (may change each year).
2026 rate and income base (independent check). MOHW’s national-pension policy page (updated 30 June 2026) states the rate rises 0.5 percentage points a year from 2026, so 2026 = 9.5%, and the monthly income base for July 2026–June 2027 is ₩410,000–₩6,590,000. That matches the figures used below.
Worked example (labelled calculated)
Assume you apply while your standard monthly income is ₩3,000,000, the due-month rate is 9.5%, and you catch up 12 months:
| Step | Amount |
|---|---|
| Monthly premium | ₩3,000,000 × 9.5% = ₩285,000 |
| 12-month catch-up | ₩285,000 × 12 = ₩3,420,000 |
Calculated illustration only. Your bill uses your actual application-month base and the rate in force in the due month. Voluntary members may hit the A-value cap before ₩3,000,000.
| Standard monthly income | Monthly premium at 9.5% | 12-month catch-up (calculated) |
|---|---|---|
| ₩1,013,000 (other voluntary-continue median from Apr 2026) | ₩96,235 | ₩1,154,820 |
| ₩3,000,000 | ₩285,000 | ₩3,420,000 |
| ₩3,193,511 (2026 A-value cap reference) | ₩303,384 | ₩3,640,608 |
| ₩6,590,000 (Jul 2026–Jun 2027 ceiling) | ₩626,050 | ₩7,512,600 |
Premiums rounded to the nearest won in the table for readability; NPS billing may round differently. Sources: NPS catch-up page formula + A-value; MOHW 9.5% and income-base band; NPS voluntary-continue median ₩1,013,000 from April 2026.
Rechecked on November 11, 2026 (National Pension Act / MOHW): Article 92(3) of the National Pension Act, as amended on 25 November 2025, sets the catch-up premium as the premium of the month in which the payment deadline falls, multiplied by the number of months, using the standard monthly income of the month you apply. MOHW’s pension-reform Q&A lists the rate path as 9.5% in 2026, 10.0% in 2027, then +0.5 point a year to 13.0% in 2033. Put that next to the NPS bill calendar above (bill around the 11th–15th of the next month, due at the end of that month): a lump-sum application made in November is normally due on December 31, 2026 at 9.5%, while one made in December is normally due in January 2027 at 10%. Worked example (our calculation): ₩3,000,000 standard monthly income × 12 months is ₩3,420,000 at 9.5% and ₩3,600,000 at 10% — ₩180,000 more. we could not confirm from an official page which rate applies to each instalment if you split the bill, and any December same-month payment option should be confirmed with NPS (1355) before you rely on it (Art. 92, National Law Information Center; MOHW Q&A; both read 11 November 2026).
Voluntary continued enrollment after 60 (임의계속가입)
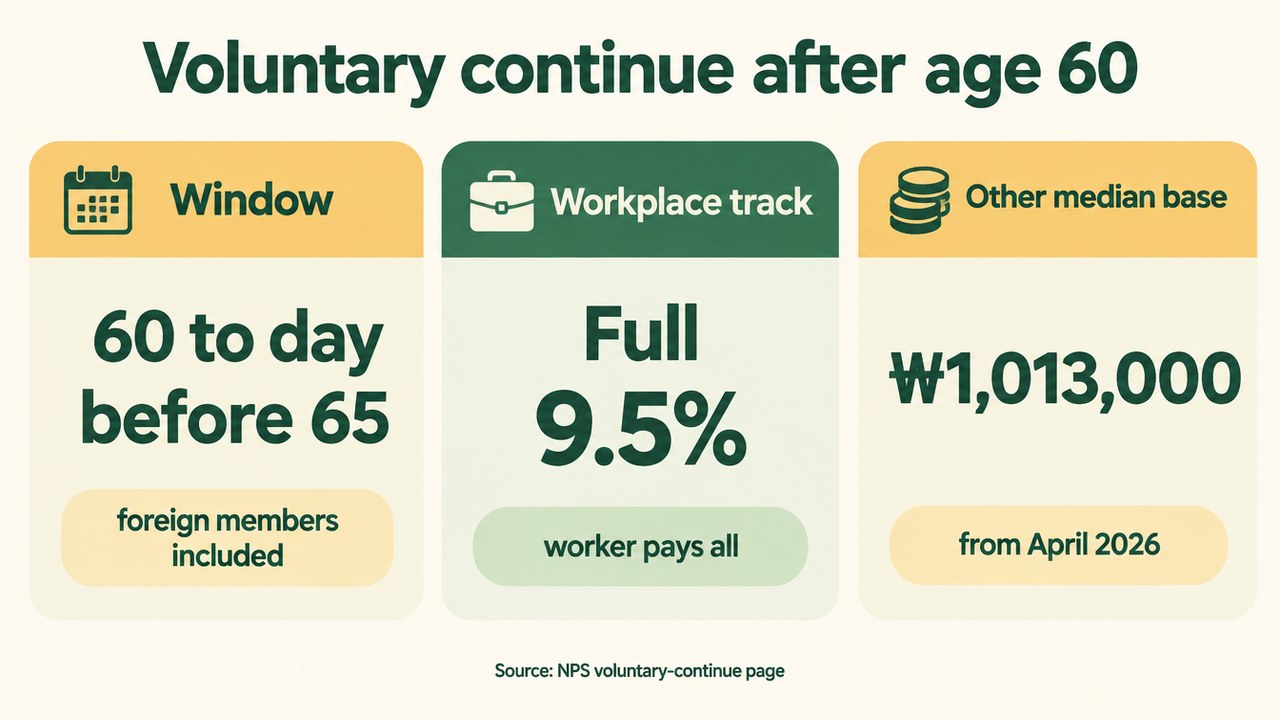
When you turn 60, ordinary membership ends. If your insured months are still short of a pension, or you want a larger benefit, NPS lets you apply to keep paying until the day before your 65th birthday. Foreign members who were or are NPS members are included. Special-occupation workers under 60 who already hold an old-age right are a separate NPS edge case — ask 1355 if that is you.
Excluded from new voluntary continue (NPS).
- Already 65 or older
- Already took a lump-sum refund because of turning 60
- Fully unpaid / fully exempt history (unpaid months can be cleared first, then you may apply)
- Already receiving old-age pension
Three flavours.
- Workplace voluntary continue — you keep working at a workplace after 60 and choose to continue. Unlike ordinary workplace members, you pay the full 9.5% yourself (not the usual 50/50 split).
- Regional voluntary continue — you continue on a regional-member income base.
- Other voluntary continue — typically people who were voluntary members; the premium base is set at or above the median regional standard monthly income. From April 2026 that median is ₩1,013,000 (NPS table: 101.3만 원).
You can apply or withdraw by visit, mail, fax, phone (with identity check), the NPS website or the mobile app. Six months of continuous non-payment can trigger an ex-officio withdrawal.
Year-end checklist (November–December 2026)
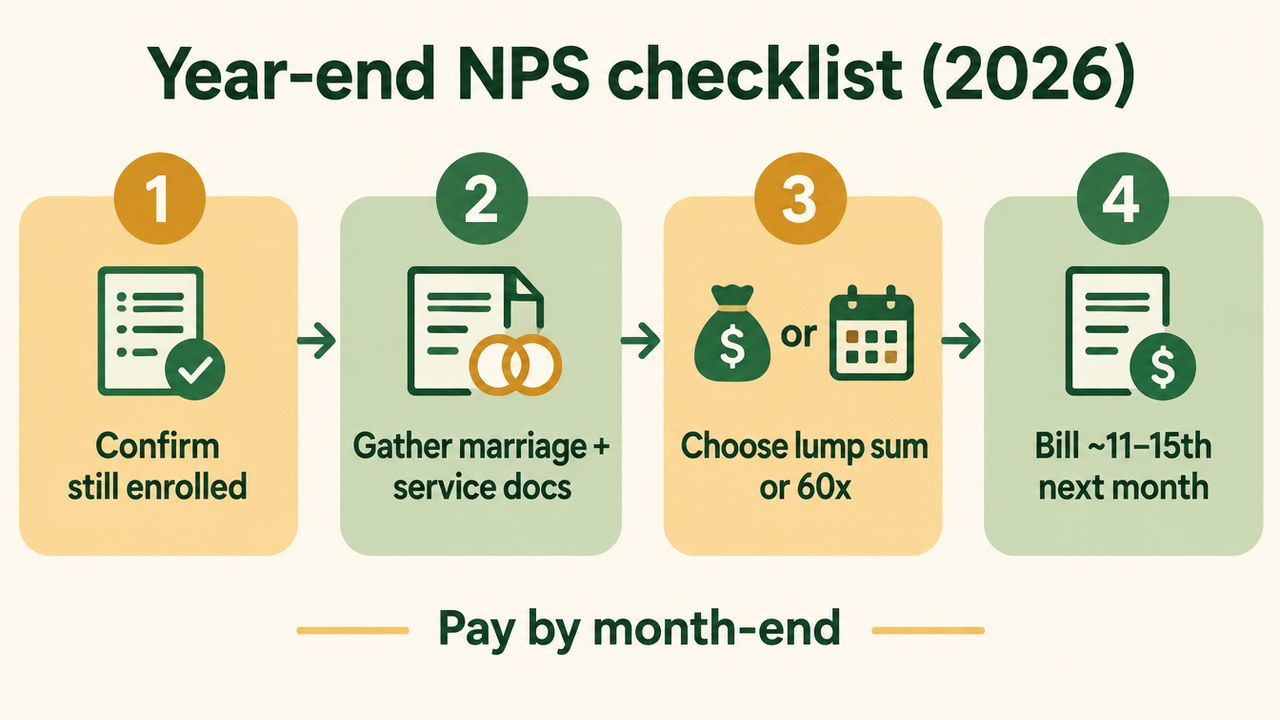
- Log into NPS (or call 1355) and list exemption / exclusion / military months still open for catch-up — remember the 119-month ceiling.
- Confirm you are currently enrolled (income-reported or voluntary / continued). Lost eligibility blocks a new catch-up application.
- Gather the detailed marriage certificate (RRNs visible) plus military or NHIS proofs if those months are in scope.
- Decide lump sum vs up to 60 installments; ask what installment interest will add.
- If you are turning 60 (or already past 60 and under 65), ask whether voluntary continue helps you cross the pension threshold — and budget the full 9.5% if you stay on a workplace track.
- Separate track: if you still have room in an IRP / pension-savings tax credit for calendar 2026, read the IRP guide — that money does not replace NPS catch-up months.
- After you apply for catch-up, watch for the bill around the 11th–15th of next month and pay by month-end.
Frequently asked questions
Q. What is the maximum Korea NPS catch-up period in 2026?
NPS limits catch-up to under 10 years — a maximum of 119 months — including qualifying military service months from 1 January 1988 when those are documented. You cannot invent months outside the listed exemption and exclusion categories.
Q. How is the 2026 catch-up premium calculated?
NPS multiplies your standard monthly income in the application month by the contribution rate in the due month, then by the number of months. The 2026 rate is 9.5% on the MOHW policy page. Voluntary members are capped using the 2026 A-value ₩3,193,511 × rate. Example: ₩3,000,000 × 9.5% × 12 months = ₩3,420,000 (calculated).
Q. Can I apply for catch-up if I already left the National Pension?
Generally no for a new application. NPS says you must currently be income-reported or voluntary/(continued) enrolled. If eligibility was lost, reinstate or enroll first, then ask again. Already-issued catch-up bills may still be payable while collection rights remain.
Q. What is voluntary continued enrollment after age 60?
It is an optional NPS track from age 60 until the day before your 65th birthday so you can finish missing months or raise your benefit. Foreign members are included. You are excluded if you already took the age-60 lump-sum refund, have a fully unpaid/exempt history, are already receiving old-age pension, or are 65+. Workplace voluntary continue means paying the full 9.5% yourself.
Q. When is the catch-up bill due and can I split it?
NPS mails the bill around the 11th–15th of the month after application; pay by the end of that month. You may pay in full or in up to 60 monthly installments, with installment interest at the 1-year time-deposit rate.
Q. Is there a deadline to pay NPS catch-up at the 2026 rate of 9.5%?
Not a formal deadline, but a practical one. The catch-up premium uses the rate of the month the bill is due (National Pension Act Art. 92(3), amended 25 November 2025), and the rate becomes 10% on January 1, 2027 — 49 days from November 13. Because NPS sends the bill around the 11th–15th of the following month with a month-end due date, a lump-sum application made by Monday, November 30, 2026 is normally due on December 31 at 9.5%. A December application is normally due in January at 10%. Confirm the due date and rate with NPS (1355) when you apply.
Related reading
- Korea health insurance after retirement: keep the employee premium
- Korea long-term care insurance grades 1–5 and the 2027 limits
- Korea payslip 2027: pension rises to 10%
Sources
- National Law Information Center, National Pension Act Article 92 (추후 납부; para. 3 amended 25 November 2025) (checked 11 November 2026)
- Ministry of Health and Welfare, Pension reform Q&A (연금개혁 Q&A) — 9.5% (2026) → 10.0% (2027) → 13.0% (2033) (checked 11 November 2026)
- National Pension Service, Additional contribution / catch-up (연금보험료의 추후납부) (checked 7 November 2026)
- National Pension Service, Voluntary continued enrollment (임의계속가입자) (checked 7 November 2026)
- Ministry of Health and Welfare, National pension membership and premiums (가입대상 및 연금보험료) — 9.5% from 2026; income base ₩410,000–₩6,590,000 for Jul 2026–Jun 2027 (checked 7 November 2026)
- National Law Information Center, MOHW notice 2026-31 income base (checked 7 November 2026)
- Haesul, Korea national pension age by birth year
- Haesul, Korea payslip: four social insurance deductions 2026
- Haesul, Korea basic pension 2026 amount and eligibility
- Haesul, Korea IRP and pension savings tax credit 2026
General information only — not financial, tax or legal advice. Written with AI assistance and checked against the sources above. NPS rules, A-values and income bases change; verify on the NPS page or by calling 1355 before you apply or pay.
3 Comments